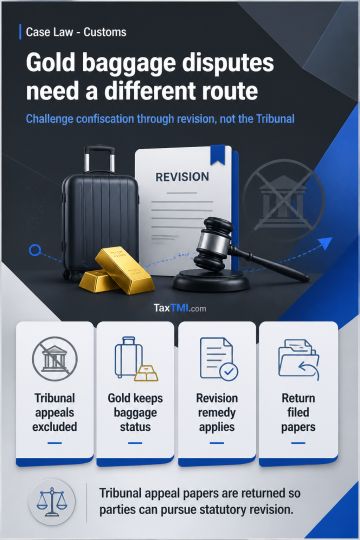
Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
Long term capital gain - allowable expenditure u/s. 48(i) - The same land has been sold in the year under consideration giving rise to long term capital gains to the three co-owners who have attempted to minimize their taxability on the said gains by resorting to the two arrangements relating to the impugned land - Claims by the assessee under the arrangements made tantamount to diversion of sale proceeds - Thus we set aside the order of ld. CIT(A) and uphold the disallowance made by the ld. AO in respect of claim of deduction - AT
Long term capital gain - allowable expenditure u/s. 48(i) - The same land has been sold in the year under consideration giving rise to long term capital gains to the three co-owners who have attempted to minimize their taxability on the said gains by resorting to the two arrangements relating to the impugned land - Claims by the assessee under the arrangements made tantamount to diversion of sale proceeds - Thus we set aside the order of ld. CIT(A) and uphold the disallowance made by the ld. AO in respect of claim of deduction - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927