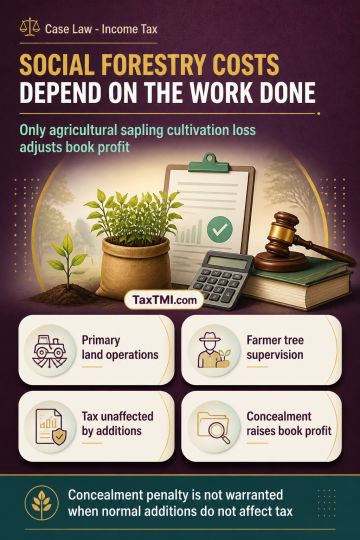
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Exemption u/s. 11 - delay in furnishing of auditor's report as required u/s. 12A - Admittedly, assessment was not completed u/s. 143(3) of the Act and, therefore, there would have been no error had the authorities below had taken up the copy of Form 10B, which was available with the Department. Thus, in our considered opinion, if the assessee was entitled to the statutory benefit, it would be incumbent upon the concerned authority to examine the admissibility of the benefit than to foreclose the assessee on technicalities. - AT
Exemption u/s. 11 - delay in furnishing of auditor's report as required u/s. 12A - Admittedly, assessment was not completed u/s. 143(3) of the Act and, therefore, there would have been no error had the authorities below had taken up the copy of Form 10B, which was available with the Department. Thus, in our considered opinion, if the assessee was entitled to the statutory benefit, it would be incumbent upon the concerned authority to examine the admissibility of the benefit than to foreclose the assessee on technicalities. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913