Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
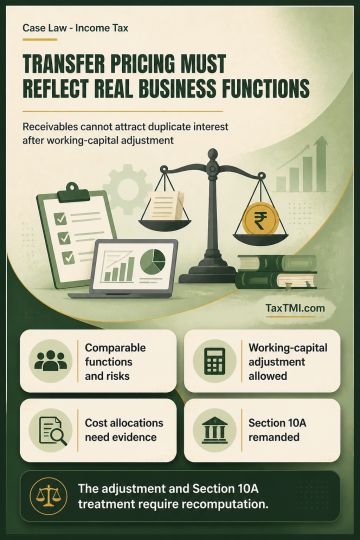
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Revision u/s 263 by CIT - AO has noted that details of expenses relating to business promotion, lease rent, commission, petrol, travelling etc. were filed by the assessee and which were checked. Therefore, in view of these facts and circumstances, we find that the Assessing Officer had carried out sufficient examination of the expenses relating to site & wages and therefore, passing of order u/s 263 on this account is also not justified. - AT
Revision u/s 263 by CIT - AO has noted that details of expenses relating to business promotion, lease rent, commission, petrol, travelling etc. were filed by the assessee and which were checked. Therefore, in view of these facts and circumstances, we find that the Assessing Officer had carried out sufficient examination of the expenses relating to site & wages and therefore, passing of order u/s 263 on this account is also not justified. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915