Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
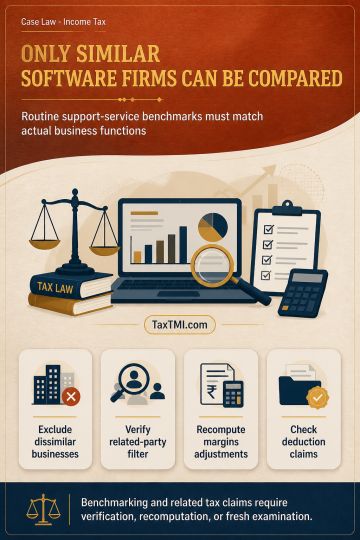
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
Revision u/s 263 by CIT - AO has noted that details of expenses relating to business promotion, lease rent, commission, petrol, travelling etc. were filed by the assessee and which were checked. Therefore, in view of these facts and circumstances, we find that the Assessing Officer had carried out sufficient examination of the expenses relating to site & wages and therefore, passing of order u/s 263 on this account is also not justified. - AT
Revision u/s 263 by CIT - AO has noted that details of expenses relating to business promotion, lease rent, commission, petrol, travelling etc. were filed by the assessee and which were checked. Therefore, in view of these facts and circumstances, we find that the Assessing Officer had carried out sufficient examination of the expenses relating to site & wages and therefore, passing of order u/s 263 on this account is also not justified. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918