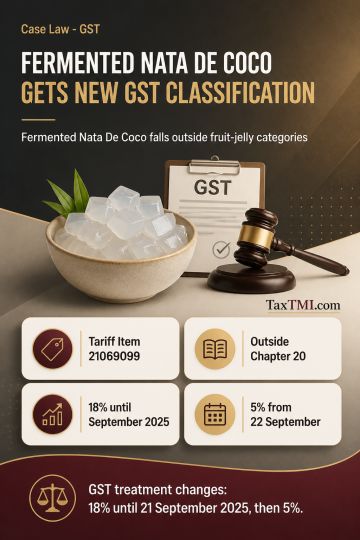
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Page of 4920
Press 'Enter' after typing page number.
1201 to 1220 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Levy of Service Tax - Business Auxiliary Service - incentives and discount support received by the appellant - It is noticed that the appellant purchases vehicles from TML and sells the same to the buyers. It is clear from the agreement that the appellant works on principal to principal basis, and not as an agent of TML - The service tax on the amount received as incentives could not have been levied to service tax - AT
Levy of Service Tax - Business Auxiliary Service - incentives and discount support received by the appellant - It is noticed that the appellant purchases vehicles from TML and sells the same to the buyers. It is clear from the agreement that the appellant works on principal to principal basis, and not as an agent of TML - The service tax on the amount received as incentives could not have been levied to service tax - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920