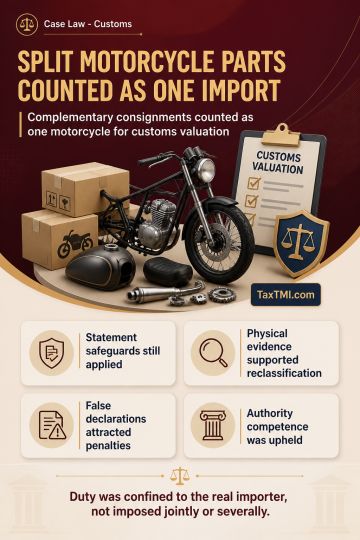
Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Bogus sales promotion expenses - The details of MR's who distributed the gifts also therefore does not establish the fact of gift having been actually distributed by the assessee. These are only self serving documents and no cognizance of the same can be taken for finding whether the assessee had in fact distributed gift articles to its customers/clients. - The reasoning of the ld. CIT(A) therefore for restricting the disallowance to the extent of 12.5% of the total expenses is therefore we hold flawed, illogical and not sustainable. - The entire expenenses in question to be disallowed - AT
Bogus sales promotion expenses - The details of MR's who distributed the gifts also therefore does not establish the fact of gift having been actually distributed by the assessee. These are only self serving documents and no cognizance of the same can be taken for finding whether the assessee had in fact distributed gift articles to its customers/clients. - The reasoning of the ld. CIT(A) therefore for restricting the disallowance to the extent of 12.5% of the total expenses is therefore we hold flawed, illogical and not sustainable. - The entire expenenses in question to be disallowed - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927