Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
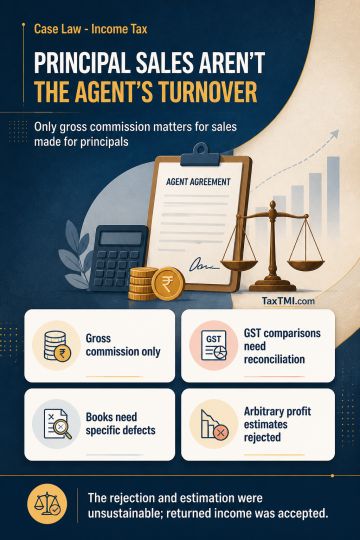
Accrual of income - Difference between the receipts as per books and form No.26AS - Assessee has shown turnover of Rs.10.09 crores, declaring GP at 9.16% and Net Profit of 3% during the year. Having disclosed such huge turnover, and disclosed appropriate net profit and having duly explained the difference in the turnover, as reflected in its books and in Form No.26AS there is no reason to believe that the assessee had wrongly not disclosed sales on these very small amount of Rs.3.00 lakhs and Rs.21 lakhs (approximately) from the aforesaid two parties. - AT
Accrual of income - Difference between the receipts as per books and form No.26AS - Assessee has shown turnover of Rs.10.09 crores, declaring GP at 9.16% and Net Profit of 3% during the year. Having disclosed such huge turnover, and disclosed appropriate net profit and having duly explained the difference in the turnover, as reflected in its books and in Form No.26AS there is no reason to believe that the assessee had wrongly not disclosed sales on these very small amount of Rs.3.00 lakhs and Rs.21 lakhs (approximately) from the aforesaid two parties. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896