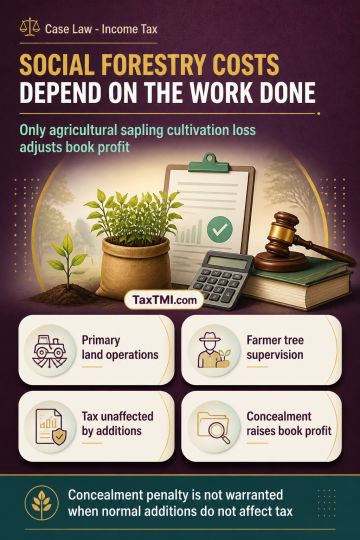
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Revision u/s 263 by CIT - addition u/s 40A ignored by AO - expenses have been incurred in cash exceeding Rs. 20,000/- per day - AO is expected to examine the provisions of section 40A(3) vis-à-vis respective transactions and determine which all these transactions are covered by the provisions of section 40A(3) and which all transactions fall under the exception as so provided in the Rule 6DD and decide accordingly. - AO has failed to examine and invoke at first place - Revision sustained - AT
Revision u/s 263 by CIT - addition u/s 40A ignored by AO - expenses have been incurred in cash exceeding Rs. 20,000/- per day - AO is expected to examine the provisions of section 40A(3) vis-à-vis respective transactions and determine which all these transactions are covered by the provisions of section 40A(3) and which all transactions fall under the exception as so provided in the Rule 6DD and decide accordingly. - AO has failed to examine and invoke at first place - Revision sustained - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899