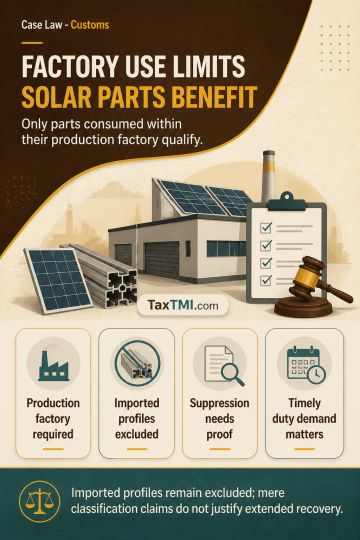
Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
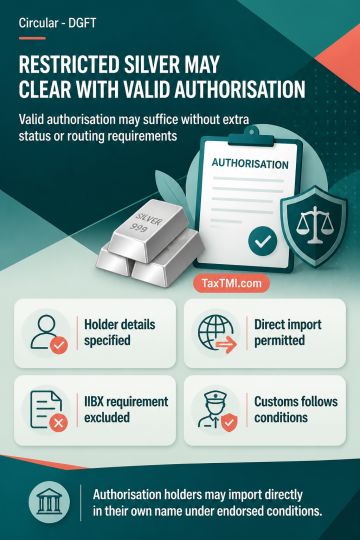
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Unexplained cash payments - There is also no evidence to suggest that cash withdrawn from ETLL was unused and kept with the assessee idle though repeatedly withdrawals were made one after the other. As per the provisions of section 292C, presumption is that cash found during the course of search belongs to assessee and burden is on the assessee to prove otherwise. Being so, we do not find any infirmity in the lower authorities bringing the cash found during the search to tax in the hands of assessee as unexplained cash. - AT
Unexplained cash payments - There is also no evidence to suggest that cash withdrawn from ETLL was unused and kept with the assessee idle though repeatedly withdrawals were made one after the other. As per the provisions of section 292C, presumption is that cash found during the course of search belongs to assessee and burden is on the assessee to prove otherwise. Being so, we do not find any infirmity in the lower authorities bringing the cash found during the search to tax in the hands of assessee as unexplained cash. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929