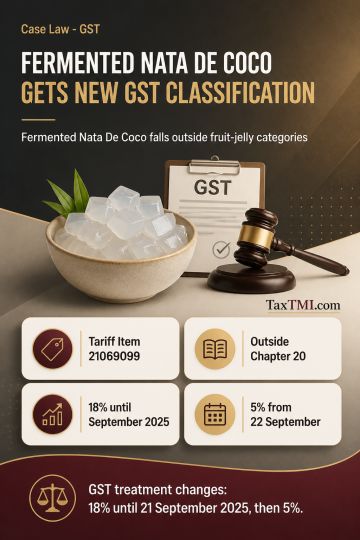
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Revision u/s 263 - deduction claim u/s 80IA and excess claim of depreciation - Case of assessee as selected for limited scrutiny - - revisional jurisdiction u/s 263 cannot be exercised by the ld PCIT as the same would tantamount to broadening the scope of jurisdiction that was originally vested with the A.O while framing the assessment u/s 143(3) of the Act in case of limited scrutiny case.. - AT
Revision u/s 263 - deduction claim u/s 80IA and excess claim of depreciation - Case of assessee as selected for limited scrutiny - - revisional jurisdiction u/s 263 cannot be exercised by the ld PCIT as the same would tantamount to broadening the scope of jurisdiction that was originally vested with the A.O while framing the assessment u/s 143(3) of the Act in case of limited scrutiny case.. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913