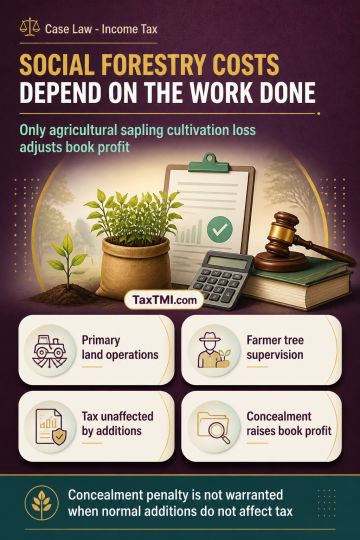
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Page of 4915
Press 'Enter' after typing page number.
1261 to 1280 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Excess depreciation - cost of development of infrastructure facility of roads/highways - Action of the Ld. AO in applying the circular retrospectively is not in order. Accordingly, the disallowance made by the Ld. AO on account of difference between the depreciation claimed and the depreciation allowed on the basis of amortization for the remaining part of the concessionaire agreement is directed to be deleted - AT
Excess depreciation - cost of development of infrastructure facility of roads/highways - Action of the Ld. AO in applying the circular retrospectively is not in order. Accordingly, the disallowance made by the Ld. AO on account of difference between the depreciation claimed and the depreciation allowed on the basis of amortization for the remaining part of the concessionaire agreement is directed to be deleted - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915