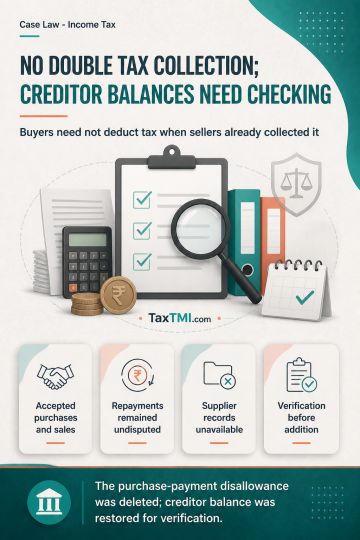
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
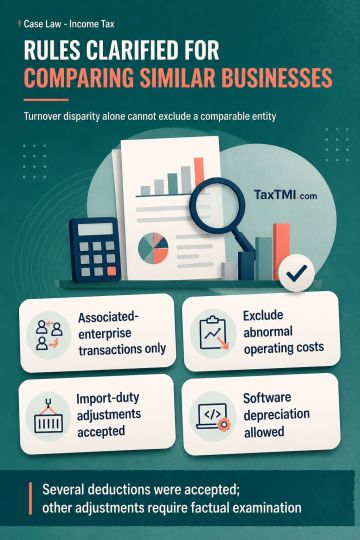
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Levy of penalty u/s 271(1)(c) - The Assessing Officer has to record satisfaction before initiating penalty proceedings and the penalty proceedings are subject to judicial scrutiny independent of additions/disallowances made under assessment proceedings. Therefore, levy of penalty for the reason that the addition/disallowance has been accepted by the assessee is not sustainable ground - AT
Levy of penalty u/s 271(1)(c) - The Assessing Officer has to record satisfaction before initiating penalty proceedings and the penalty proceedings are subject to judicial scrutiny independent of additions/disallowances made under assessment proceedings. Therefore, levy of penalty for the reason that the addition/disallowance has been accepted by the assessee is not sustainable ground - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913