Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
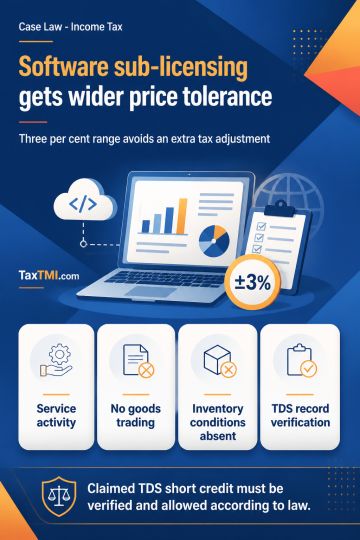
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Jurisdiction by AO to suo-moto convert protective assessment into substantive assessment post completion of original assessment proceedings - Once the ld CIT(A) was ceased of the matter, the AO could have brought this up before the ld CIT(A) and sought necessary directions. Where however, the AO still hold the belief to take suo-moto action to convert protective assessment into substantive assessment, he could have invoked his jurisdiction in terms of section 147 on satisfaction of conditions specified therein and in absence of thereof, the present action of the AO cannot be sustained in the eyes of law. - AT
Jurisdiction by AO to suo-moto convert protective assessment into substantive assessment post completion of original assessment proceedings - Once the ld CIT(A) was ceased of the matter, the AO could have brought this up before the ld CIT(A) and sought necessary directions. Where however, the AO still hold the belief to take suo-moto action to convert protective assessment into substantive assessment, he could have invoked his jurisdiction in terms of section 147 on satisfaction of conditions specified therein and in absence of thereof, the present action of the AO cannot be sustained in the eyes of law. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905