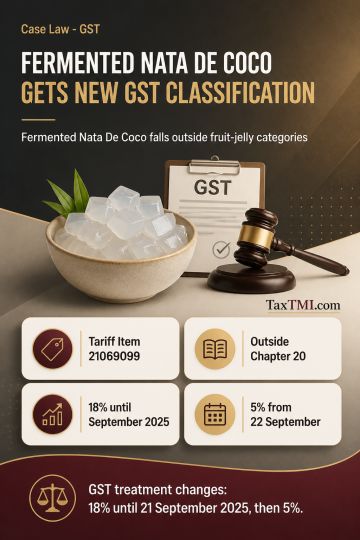
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Validity of assessment order - The limitation for passing of such assessment order is four years from the end of the year containing the period to which the return relates. Since the assessment period is 01.04.2015 to 31.03.2016, the four year limitation period would expire on 31.03.2020. Therefore, if the assessment order was required to be passed under section 23(2) of the MVAT Act for the aforesaid assessment period, it had to be passed on or before 31.03.2020. - Those were passed beyond the limitation period of 31.03.2020 and thus are non est in the eye of law. - HC
Validity of assessment order - The limitation for passing of such assessment order is four years from the end of the year containing the period to which the return relates. Since the assessment period is 01.04.2015 to 31.03.2016, the four year limitation period would expire on 31.03.2020. Therefore, if the assessment order was required to be passed under section 23(2) of the MVAT Act for the aforesaid assessment period, it had to be passed on or before 31.03.2020. - Those were passed beyond the limitation period of 31.03.2020 and thus are non est in the eye of law. - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910