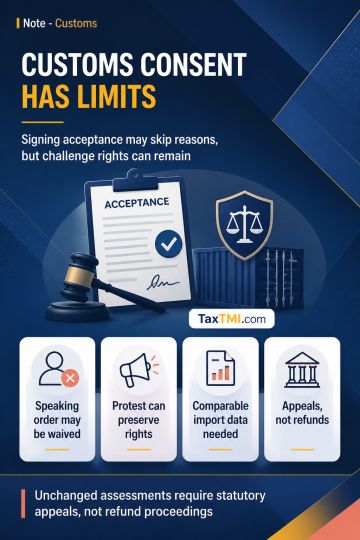
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
Refund of ITC or claim of duty draw back - the petitioner, for the month of July, 2017 has opted to stick with the claim of duty draw back seeing as the amount of drawback is higher than the ITC for the months of August and September, 2017 - On a plain reading of Section 54 (3) it is found that the claim of refund to be in order. - Paragraph 2.5 of the circular, insofar as it is contrary to the statutory provisions of Section 54(3) is bad in law. - HC
Refund of ITC or claim of duty draw back - the petitioner, for the month of July, 2017 has opted to stick with the claim of duty draw back seeing as the amount of drawback is higher than the ITC for the months of August and September, 2017 - On a plain reading of Section 54 (3) it is found that the claim of refund to be in order. - Paragraph 2.5 of the circular, insofar as it is contrary to the statutory provisions of Section 54(3) is bad in law. - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920