Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
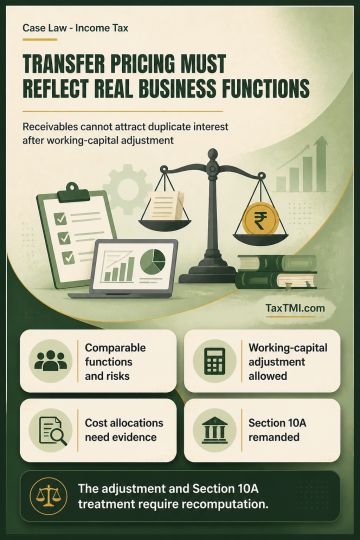
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Assessment u/s 153C - Now supposing a search is conducted in one year and documents of other person are handed over to the Assessing Officer, of other person or to the Assessing Officer with whom jurisdiction is centralized, after two years from the date of search, then for which six years the other person would show his accounts, whether for the years which are applicable for search person or for those years which are governed by the proviso. Thus, for those years which are governed by the proviso because the Income Tax Rules say so. - AT
Assessment u/s 153C - Now supposing a search is conducted in one year and documents of other person are handed over to the Assessing Officer, of other person or to the Assessing Officer with whom jurisdiction is centralized, after two years from the date of search, then for which six years the other person would show his accounts, whether for the years which are applicable for search person or for those years which are governed by the proviso. Thus, for those years which are governed by the proviso because the Income Tax Rules say so. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915