Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
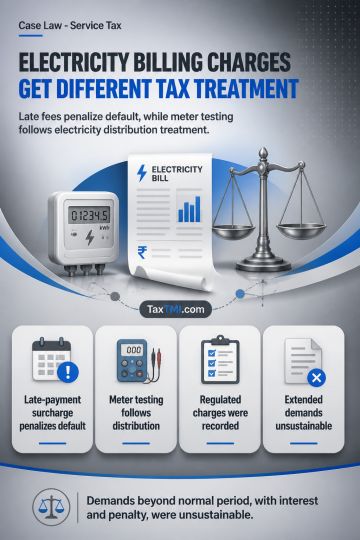
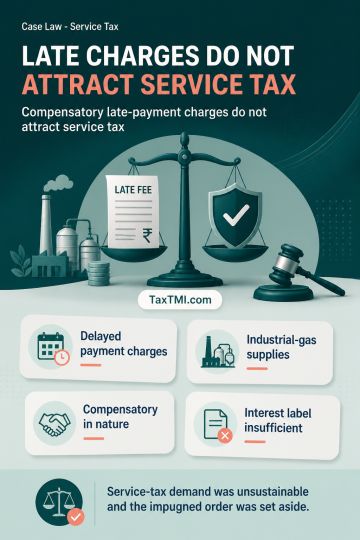
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Disallowance of provision for professional cost - Accounts of the company are audited by reputed CA firm and therefore it cannot be said that it is an inadvertent error. Even if the same is considered as an inadvertent error, the assessee has not taken any step to revise the return of income. Therefore, we fully concur with the findings of the Ld. CIT(A) that assessee has not adopted consistent accounting principle on year to year basis and it is not open to the assessee to claim the expense on provision basis in one year and on accrual basis in the other year. - AT
Disallowance of provision for professional cost - Accounts of the company are audited by reputed CA firm and therefore it cannot be said that it is an inadvertent error. Even if the same is considered as an inadvertent error, the assessee has not taken any step to revise the return of income. Therefore, we fully concur with the findings of the Ld. CIT(A) that assessee has not adopted consistent accounting principle on year to year basis and it is not open to the assessee to claim the expense on provision basis in one year and on accrual basis in the other year. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913