Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
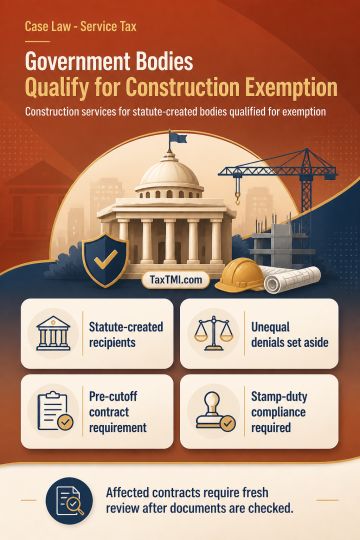
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Page of 4913
Press 'Enter' after typing page number.
1821 to 1840 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Undisclosed stock - relevant assessment year - additions for the financial year 2012-2013 relevant to assessment year 2013-2014 - Once the statements have been accepted by the survey team the tax should be calculated by them for the relevant years accepted by the assessee. In view of the above findings noted by us, it should be taxed in the assessment year 2012-2013. - Additions deleted.
Undisclosed stock - relevant assessment year - additions for the financial year 2012-2013 relevant to assessment year 2013-2014 - Once the statements have been accepted by the survey team the tax should be calculated by them for the relevant years accepted by the assessee. In view of the above findings noted by us, it should be taxed in the assessment year 2012-2013. - Additions deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913