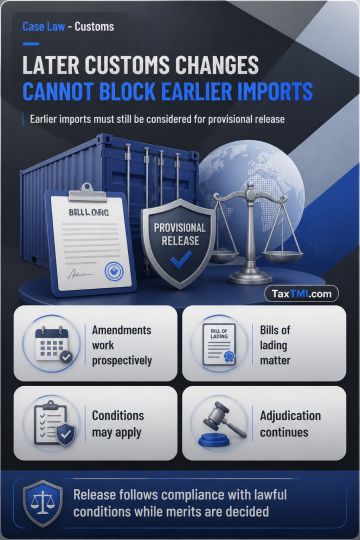
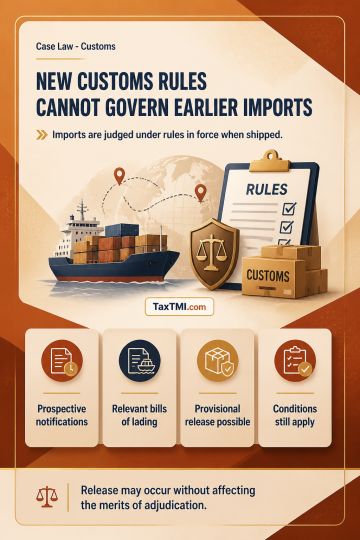
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
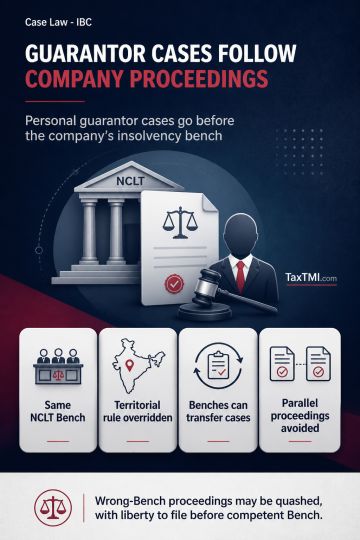
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
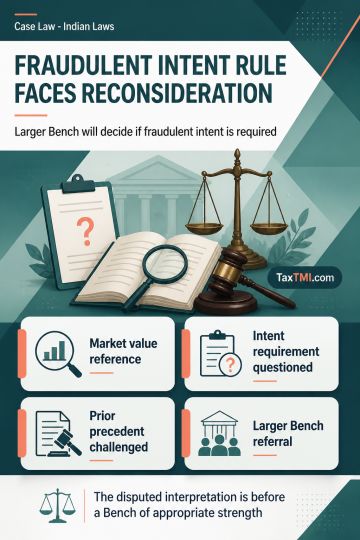
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
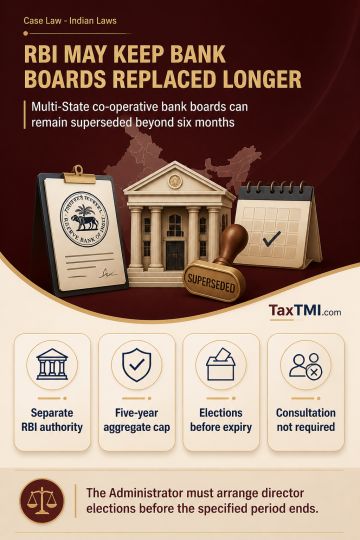
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Undisclosed stock - relevant assessment year - additions for the financial year 2012-2013 relevant to assessment year 2013-2014 - Once the statements have been accepted by the survey team the tax should be calculated by them for the relevant years accepted by the assessee. In view of the above findings noted by us, it should be taxed in the assessment year 2012-2013. - Additions deleted.
Undisclosed stock - relevant assessment year - additions for the financial year 2012-2013 relevant to assessment year 2013-2014 - Once the statements have been accepted by the survey team the tax should be calculated by them for the relevant years accepted by the assessee. In view of the above findings noted by us, it should be taxed in the assessment year 2012-2013. - Additions deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908