Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
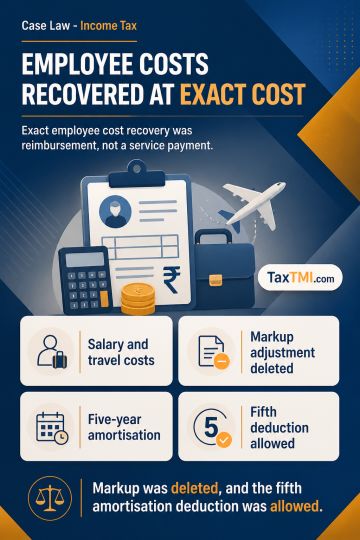
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
Disallowance u/s 40(a)(ia) - non-deduction of tax at source (TDS) from the payment made towards Harvesting charges - assessee is acting on behalf of the farmers for Sugarcane procurement - assessee is not liable to deduct tax at source from the harvesting charges paid by it on behalf of the farmers in both the years.
Disallowance u/s 40(a)(ia) - non-deduction of tax at source (TDS) from the payment made towards Harvesting charges - assessee is acting on behalf of the farmers for Sugarcane procurement - assessee is not liable to deduct tax at source from the harvesting charges paid by it on behalf of the farmers in both the years.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927