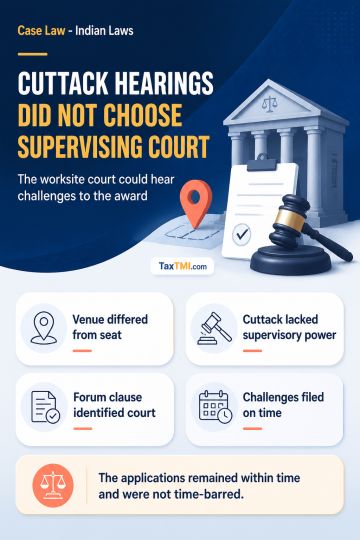
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
Entitled to interest on the amount of refund u/s 244A - Refund of excess TDS - there is no reason to deny payment of interest to the deductor who had deducted tax at source and deposited the same with the Treasury.
Entitled to interest on the amount of refund u/s 244A - Refund of excess TDS - there is no reason to deny payment of interest to the deductor who had deducted tax at source and deposited the same with the Treasury.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881