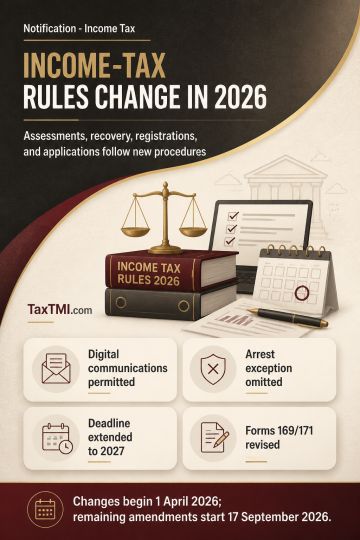
Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
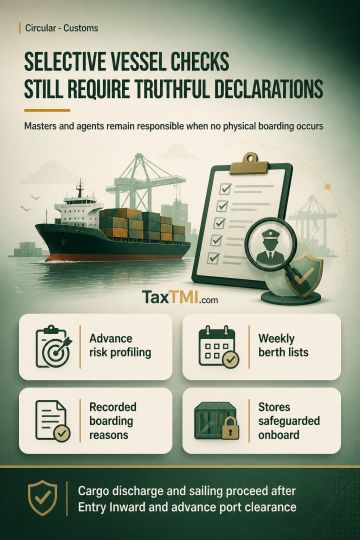
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Penalty u/s 271(1)(c) - voluntary surrender on account of long term capital gain on sale of shares during assessment proceedings - the surrender made by the assessee is voluntary, for which only addition can be made and penalty u/s 271(1)(c) cannot be initiated.
Penalty u/s 271(1)(c) - voluntary surrender on account of long term capital gain on sale of shares during assessment proceedings - the surrender made by the assessee is voluntary, for which only addition can be made and penalty u/s 271(1)(c) cannot be initiated.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915