Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
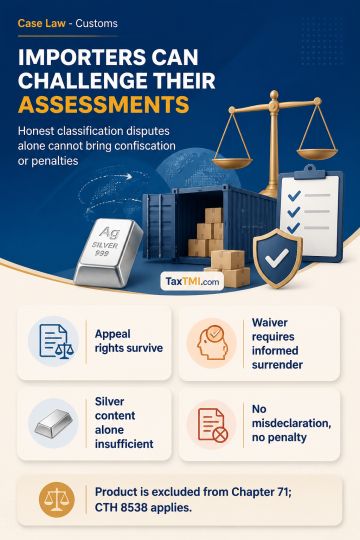
Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
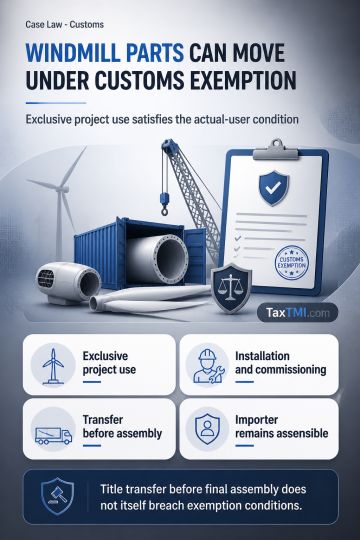
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Profiteering - Respondent has issued incorrect invoices while selling the above product to his customers as he had not correctly shown the basic price which he should have legally charged from them. The Respondent has also compelled them to pay additional GST on the increased price through the incorrect tax invoices which would have otherwise resulted in further benefit to the customers which he has failed to pass on - liable to penalty.
Profiteering - Respondent has issued incorrect invoices while selling the above product to his customers as he had not correctly shown the basic price which he should have legally charged from them. The Respondent has also compelled them to pay additional GST on the increased price through the incorrect tax invoices which would have otherwise resulted in further benefit to the customers which he has failed to pass on - liable to penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4863