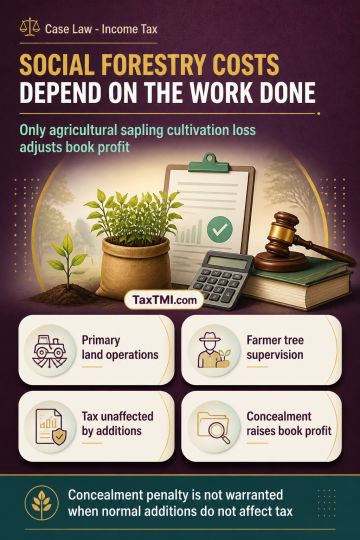
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Page of 4912
Press 'Enter' after typing page number.
1201 to 1220 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Set-off of carried forward depreciation - When such claim could not have been made u/s 32(1), then there is no question of any carry forward of such depreciation for reason of the claim for depreciation having never arisen in that previous year relevant to the previous assessment year.
Set-off of carried forward depreciation - When such claim could not have been made u/s 32(1), then there is no question of any carry forward of such depreciation for reason of the claim for depreciation having never arisen in that previous year relevant to the previous assessment year.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912