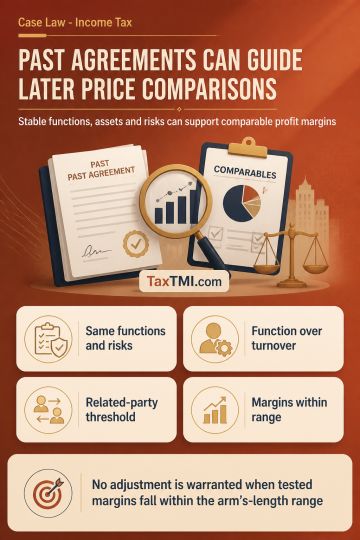
Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
Set-off of carried forward depreciation - When such claim could not have been made u/s 32(1), then there is no question of any carry forward of such depreciation for reason of the claim for depreciation having never arisen in that previous year relevant to the previous assessment year.
Set-off of carried forward depreciation - When such claim could not have been made u/s 32(1), then there is no question of any carry forward of such depreciation for reason of the claim for depreciation having never arisen in that previous year relevant to the previous assessment year.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899