Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
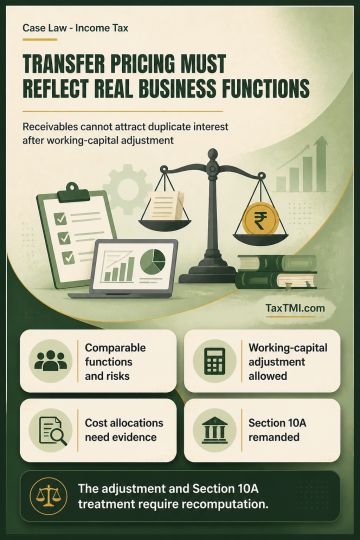
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Refund of Terminal Excise Duty (TED) - The fact that the petitioner could or could not get refund under the CENVAT Credit Rules or under the provisions of the Central Excise Act is not relevant - The argument that since excise duty was not paid via cash but was paid by utilizing the CENVAT credit route and hence, the petitioner would not be entitled to claim refund is unsustainable.
Refund of Terminal Excise Duty (TED) - The fact that the petitioner could or could not get refund under the CENVAT Credit Rules or under the provisions of the Central Excise Act is not relevant - The argument that since excise duty was not paid via cash but was paid by utilizing the CENVAT credit route and hence, the petitioner would not be entitled to claim refund is unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915