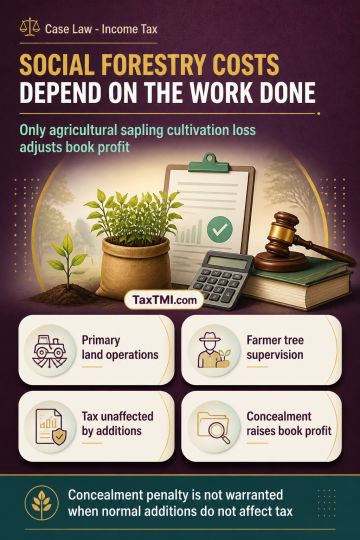
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
Penalty proceedings u/s 271(1)(b) - non-compliance of statutory notices - it was difficult to comply to the various notices on short dates - compliances had been made through replies filed through dak or registered post though belatedly - All these facts and circumstances under any prudence do constitute reasonable cause u/s 273B - No penalty - AT
Penalty proceedings u/s 271(1)(b) - non-compliance of statutory notices - it was difficult to comply to the various notices on short dates - compliances had been made through replies filed through dak or registered post though belatedly - All these facts and circumstances under any prudence do constitute reasonable cause u/s 273B - No penalty - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915