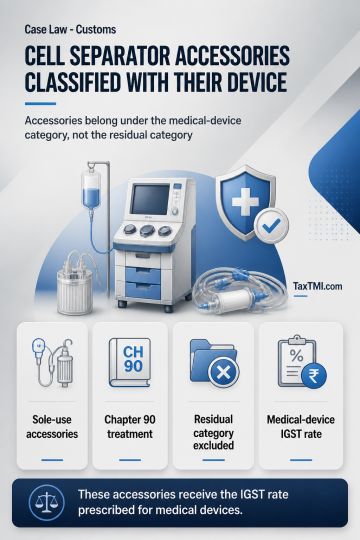
Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
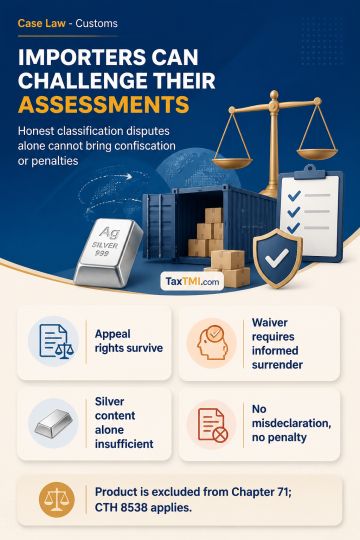
Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
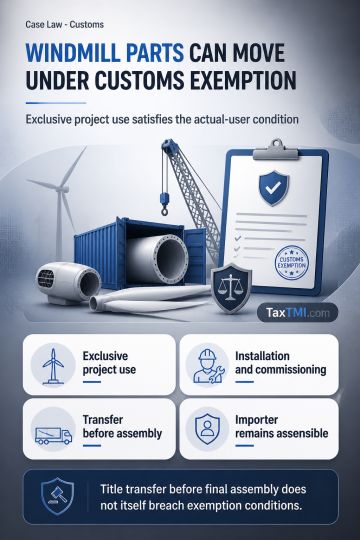
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Depreciation on the asset which were claimed as application u/s 11 at the time of purchase - ultimately assessee is a charitable institution and its income for tax purposes is required to be determined by taking into consideration provisions of Section 11 of the Act of 1961 after extending normal depreciation and deductions from its gross income. - HC
Depreciation on the asset which were claimed as application u/s 11 at the time of purchase - ultimately assessee is a charitable institution and its income for tax purposes is required to be determined by taking into consideration provisions of Section 11 of the Act of 1961 after extending normal depreciation and deductions from its gross income. - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4863