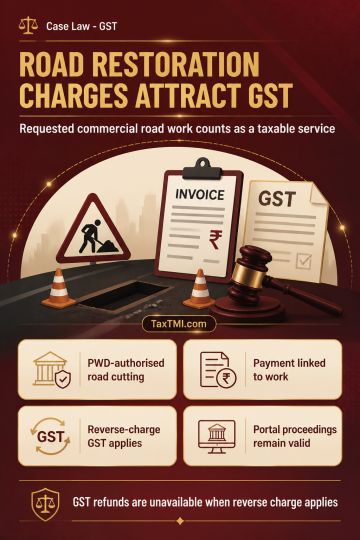
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Levy of penalty u/s 271B read with section 274(1) - technical snag while upholding the tax audit report electronically - aking into the fact that the audit report has subsequently been uploaded electronically and also hard copy has been furnished before the AO before the completion of the assessment proceedings, no penalty - AT
Levy of penalty u/s 271B read with section 274(1) - technical snag while upholding the tax audit report electronically - aking into the fact that the audit report has subsequently been uploaded electronically and also hard copy has been furnished before the AO before the completion of the assessment proceedings, no penalty - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927