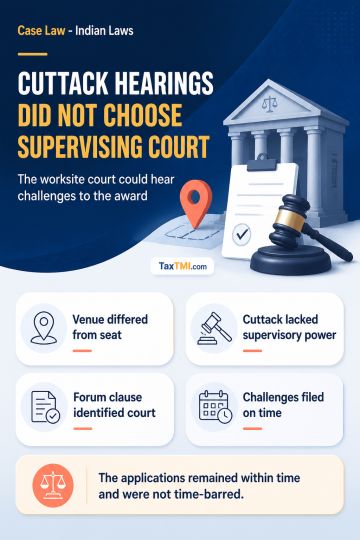
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
Where the Revenue urges that the amount of share application money has been received from bogus shareholders then it is for the Income Tax Officer to proceed by reopening the assessment of such shareholders and assessing them to tax in accordance with law. It does not entitle the Revenue to add the same to the assessee's income as unexplained cash credit - HC
Where the Revenue urges that the amount of share application money has been received from bogus shareholders then it is for the Income Tax Officer to proceed by reopening the assessment of such shareholders and assessing them to tax in accordance with law. It does not entitle the Revenue to add the same to the assessee's income as unexplained cash credit - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881