Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Final benami adjudication bars contradictory tax-evasion prosecution where settlement findings confirm full disclosure and cooperation without conceal...
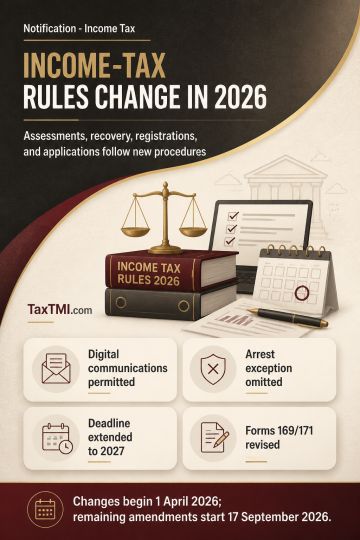
Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
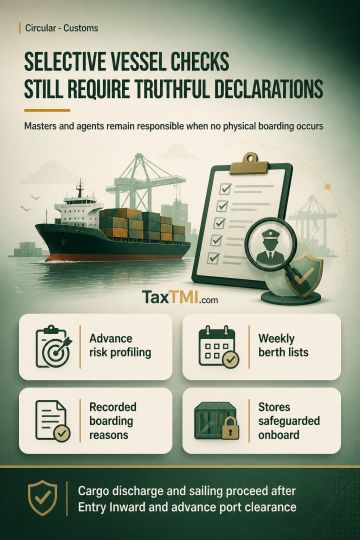
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Whether the Tribunal was justified in holding that irrespective of the purpose for which the duty has been granted in respect of the excess production of sugar during the lean period, refund on account of the exemption of notification would be subject to the principle of unjust enrichment? - Held Yes - HC
Whether the Tribunal was justified in holding that irrespective of the purpose for which the duty has been granted in respect of the excess production of sugar during the lean period, refund on account of the exemption of notification would be subject to the principle of unjust enrichment? - Held Yes - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915