Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
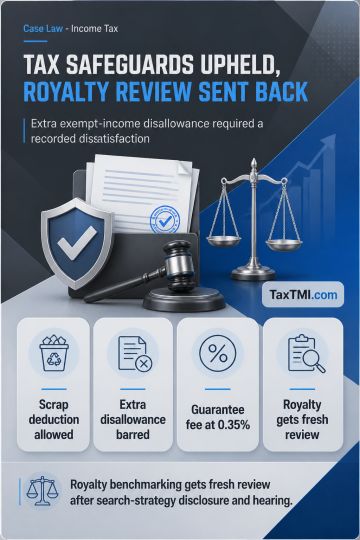
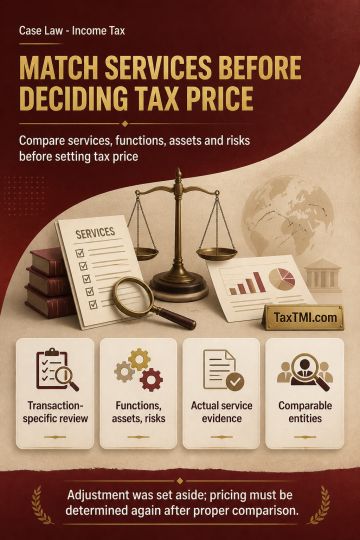
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Cash refund on accumulated cenvat credit under Rule 5 of the CCR, 2004 - If the EP copies of the shipping bills have been misplaced, the photocopies of the original EP copies duly attested by the exporter can also be produced - AT
Cash refund on accumulated cenvat credit under Rule 5 of the CCR, 2004 - If the EP copies of the shipping bills have been misplaced, the photocopies of the original EP copies duly attested by the exporter can also be produced - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929