Digital onboarding for overseas individual investors permits remote KYC from FATF-compliant countries while preserving verification and audit safeguar...
Real estate insolvency compliance requires access to regulatory records, prominent site disclosures and continued adherence to property law during res...
Brand promotion expenditure requires an established associated-enterprise arrangement for transfer pricing, while management cross-charges must accoun...
Reassessment after the ordinary limitation period requires the escaped-income threshold and independent sanction, without expanding jurisdiction throu...
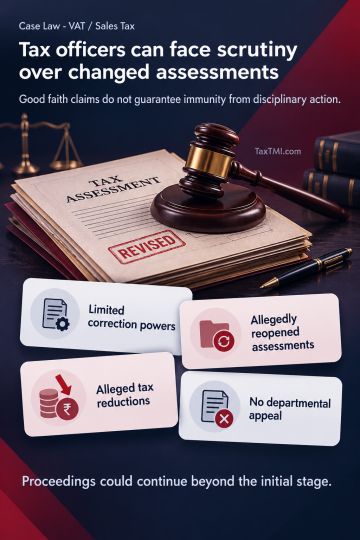
Quasi-judicial rectification powers do not confer absolute immunity from disciplinary action for negligent or reckless conduct or conduct intended to confer undue favour. Disciplinary scrutiny concerns an officer's conduct independently of a departmental appeal against the legality of the order. Allegations that limited rectification powers were used to reopen concluded assessments and substantially reduce confirmed tax demands disclosed a prima facie basis for factual scrutiny in a departmental enquiry. A plea of good faith and the absence of a departmental appeal did not justify terminating the proceedings at the threshold.
Quasi-judicial rectification powers do not confer absolute immunity from disciplinary action for negligent or reckless conduct or conduct intended to confer undue favour. Disciplinary scrutiny concerns an officer's conduct independently of a departmental appeal against the legality of the order. Allegations that limited rectification powers were used to reopen concluded assessments and substantially reduce confirmed tax demands disclosed a prima facie basis for factual scrutiny in a departmental enquiry. A plea of good faith and the absence of a departmental appeal did not justify terminating the proceedings at the threshold.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4951




 Get Daily Updates





