Preferential tariff claims under trade agreements require agreement-consistent origin checks, with safeguards against automatic denial for subsequent ...
Suppressed outward supplies require transaction-wise verification and reasoned findings before diary entries can support tax and penalty determination...
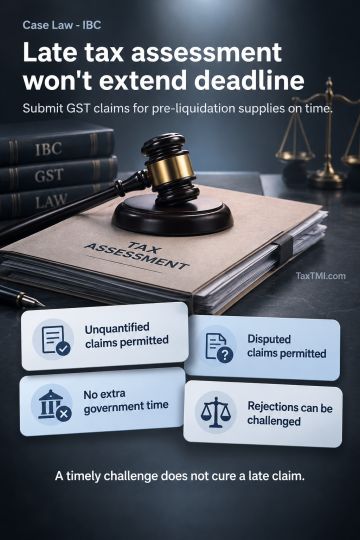
GST claims arising from supplies before liquidation may be submitted when unquantified or disputed; later assessment does not restart the claim-submission period. The liquidation regulations cover claims existing at the liquidation commencement date, so liability arising only on a later assessment falls outside those regulations. The liquidator has no regulatory power to accept claims after the deadline. Section 42 permits a challenge to the liquidator's decision, not a fresh opportunity to submit a claim. Section 60(5) operates within the Code's time-bound framework, while Section 238A does not cure late claim submission where the challenge to rejection is timely. Even assuming delay can be condoned, sufficient cause must explain the delay consistently with orderly liquidation; government status grants no additional time.
GST claims arising from supplies before liquidation may be submitted when unquantified or disputed; later assessment does not restart the claim-submission period. The liquidation regulations cover claims existing at the liquidation commencement date, so liability arising only on a later assessment falls outside those regulations. The liquidator has no regulatory power to accept claims after the deadline. Section 42 permits a challenge to the liquidator's decision, not a fresh opportunity to submit a claim. Section 60(5) operates within the Code's time-bound framework, while Section 238A does not cure late claim submission where the challenge to rejection is timely. Even assuming delay can be condoned, sufficient cause must explain the delay consistently with orderly liquidation; government status grants no additional time.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4949


 Get Daily Updates