Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Benami accommodation entries can remain subject to attachment despite income-tax relief and absence of witness cross-examination
    Interest on delayed customs refunds follows confirmed refund entitlement when an unjust enrichment objection no longer survives.
    Natural justice in second-hand machinery valuation requires reasons for rejecting cross-examination and consideration of requests for import records.
    Corporate suit authorisation and subsequent board resolutions: production may be permitted without prejudging admissibility or maintainability.
    Subsidiary debt cannot be attributed to a parent solely through ownership or a unilateral letter concerning excluded transfer liabilities.
    Complainant participation in insolvency disciplinary appeals is not automatically mandatory, while later representative changes do not undo valid acts...
    GST claims for pre-liquidation supplies must be submitted on time even if tax is assessed after liquidation begins.
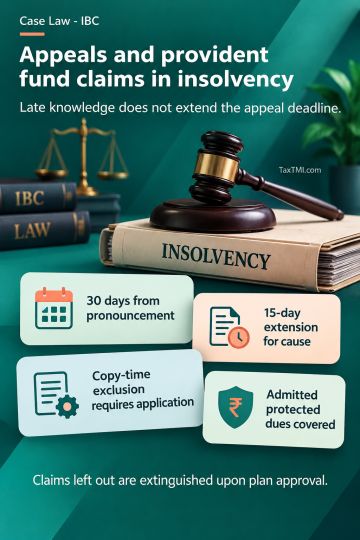
    Resolution plan appeal deadlines remain fixed despite delayed knowledge, while unprovided provident fund claims may be extinguished.
    Direct appeals against provisional attachment under money laundering law fall outside appellate jurisdiction, which covers adjudicating authority orde...
    Statutory substitution enables asset reconstruction companies acquiring security cheques for consideration to continue pending cheque-dishonour prosec...
    Corporate guarantees without fees may attract GST, with deemed valuation applying only after taxable supply is established.
    Cross-border secondment reimbursements require separate employment and knowledge-transfer analysis before taxation as included services under the Indi...
    GST appeal pre-deposits may be met by verified earlier payments after demand reduction, but filing fees remain separate.
    Inter-society interest payments by co-operative banks qualify for TDS exemption, subject to applicable statutory turnover and interest thresholds.
    Input tax credit and supplier non-payment: credit cannot be reversed mechanically without transaction scrutiny and supplier recovery review
    Real estate allottee insolvency claims require revised Form CA, while stated relief preferences do not create enforceable rights.
    REIT depository receipts face non-resident holding rules, exchange listing requirements and unitholder approval for fresh issues
    Export payments through repatriable accounts, permitted set-offs and net retention satisfy payment conditions; unrealised goods proceeds affect refund...
    Input tax credit on used vehicle trading expenses remains available under the GST margin scheme, subject to statutory conditions.
    GST exemptions and valuation rules clarify treatment of grant-funded research, vehicle lease recoveries, bank fund transfers and co-lending.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Telegram Get Daily Updates

Appeals against resolution plan approval must be filed within 30...

Resolution plan appeal deadlines remain fixed despite delayed knowledge, while unprovided provident fund claims may be extinguished.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

IBC November 5, 2026 Case Laws AT
Appeals against resolution plan approval must be filed within 30 days of pronouncement, with a further 15 days available for sufficient cause. Delayed knowledge or failure to notify claimants does not extend the outer limit, and exclusion of time for obtaining a certified copy requires an application. The resolution professional must inform claimants of the payment principle or formula after approval; non-compliance may invite regulatory action. Provident fund sums excluded from the liquidation estate fall outside the distribution waterfall, and admitted protected dues must be provided for in full. Interest and damages undetermined before insolvency proceedings commence are contingent liabilities that creditors may leave unprovided for. Claims not provided for are extinguished upon plan approval; admission and verification disputes may be challenged during insolvency proceedings.

Topics

Acts Income Tax