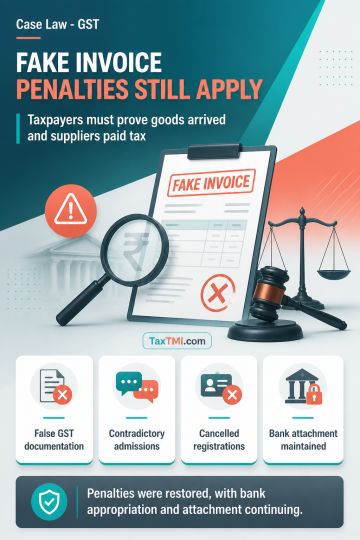
Fake-invoice penalties remain available where taxpayer admissions and records establish unsupported input tax credit claims and false GST documentatio...
Finality of a prior remand adjudication bars re-agitation of continued custody where the earlier determination was not disturbed, while preserving the option to seek regular bail. A complaint filed within the period prescribed by section 187 of the BNSS satisfies the requirement for statutory/default bail purposes; cognizance need not be taken within that period. Setting aside cognizance for failure to provide a pre-cognizance hearing under section 223 of the BNSS does not make further remand illegal or create an entitlement to statutory release. The appropriate recourse remains a merits-based regular bail application.
Finality of a prior remand adjudication bars re-agitation of continued custody where the earlier determination was not disturbed, while preserving the option to seek regular bail. A complaint filed within the period prescribed by section 187 of the BNSS satisfies the requirement for statutory/default bail purposes; cognizance need not be taken within that period. Setting aside cognizance for failure to provide a pre-cognizance hearing under section 223 of the BNSS does not make further remand illegal or create an entitlement to statutory release. The appropriate recourse remains a merits-based regular bail application.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4949










 Get Daily Updates


