Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
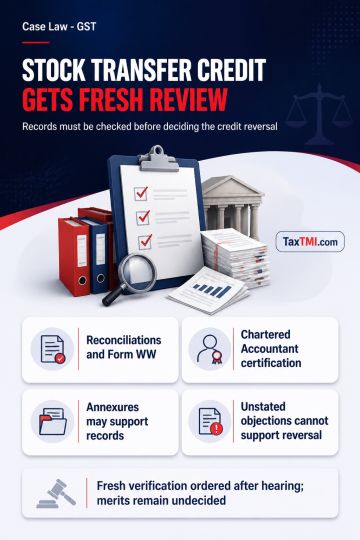
Input tax credit reversal on stock transfers requires verification of reconciliations, Form WW and Chartered Accountant certification supporting inter-State purchase claims. Annexures supplied in replies, appeal materials and fuller reconciliation may constitute supporting records. A reversal cannot rest on an objection, such as lack of proof of manufacture outside the State, that was absent from the show-cause notices. The input tax credit reversal issue was remanded for fresh verification after hearing the assessee, who may provide additional particulars; merits remained undecided.
Input tax credit reversal on stock transfers requires verification of reconciliations, Form WW and Chartered Accountant certification supporting inter-State purchase claims. Annexures supplied in replies, appeal materials and fuller reconciliation may constitute supporting records. A reversal cannot rest on an objection, such as lack of proof of manufacture outside the State, that was absent from the show-cause notices. The input tax credit reversal issue was remanded for fresh verification after hearing the assessee, who may provide additional particulars; merits remained undecided.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927