Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
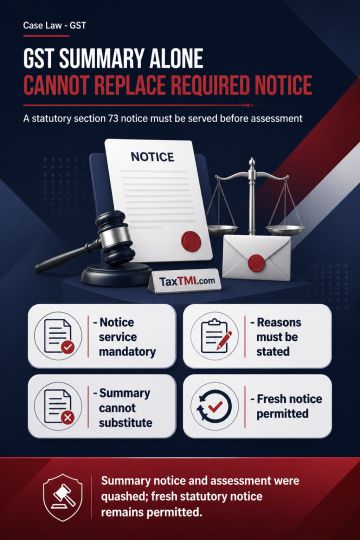
Service of a statutory show cause notice under section 73 is mandatory; the notice must state the reasons for initiating proceedings. Rule 142 requires the statutory notice to be accompanied by a prescribed summary, but the summary cannot substitute for service of the notice itself. Where only the summary was served, the mandatory notice procedure was not complied with. The summary notice and assessment founded solely on it were quashed, while the competent authority retained liberty to issue a fresh statutory notice with its summary and proceed in accordance with law.
Service of a statutory show cause notice under section 73 is mandatory; the notice must state the reasons for initiating proceedings. Rule 142 requires the statutory notice to be accompanied by a prescribed summary, but the summary cannot substitute for service of the notice itself. Where only the summary was served, the mandatory notice procedure was not complied with. The summary notice and assessment founded solely on it were quashed, while the competent authority retained liberty to issue a fresh statutory notice with its summary and proceed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927