Approved gratuity fund provisions remain deductible despite general actual-payment requirements, preventing revision of the allowed gratuity deduction...
Verification of intangible software expenditure and duplicated disallowances requires record-based reassessment before depreciation and income computa...
Cash receipt aggregation requires a single transaction, event or occasion; separate partner capital contributions cannot attract cash-receipt penaltie...
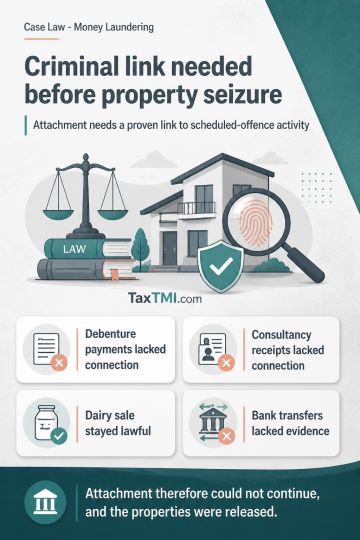
Proceeds of crime must be property derived or obtained, directly or indirectly, from criminal activity relating to a scheduled offence. Receipts under debenture subscription and consultancy agreements received before the relevant bank disbursal lacked the required nexus. The unpaid consideration under a pre-existing dairy-business sale agreement remained an independent lawful transaction. Banking transfers and later disbursals to legal entities cannot be characterised as proceeds of crime without cogent evidence of that nexus. Attachment therefore could not continue, and the properties were released.
Proceeds of crime must be property derived or obtained, directly or indirectly, from criminal activity relating to a scheduled offence. Receipts under debenture subscription and consultancy agreements received before the relevant bank disbursal lacked the required nexus. The unpaid consideration under a pre-existing dairy-business sale agreement remained an independent lawful transaction. Banking transfers and later disbursals to legal entities cannot be characterised as proceeds of crime without cogent evidence of that nexus. Attachment therefore could not continue, and the properties were released.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932