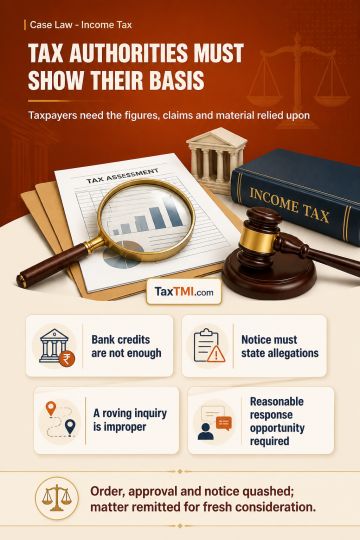
Section 148A reassessment proceedings require disclosure of the computation, relevant allegations and supporting material before an order is made under Section 148A(3). Treating all bank credits as undisclosed turnover without furnishing the computation, and relying on allegations concerning fund parking, expenses and unsecured loans that were absent from the notice, converts the process into a roving inquiry rather than one based on definite aspects. The Section 148A(3) order, prior approval and Section 148 notice were quashed and remitted for fresh consideration after disclosure of the relied-upon material and a reasonable opportunity to respond.
Section 148A reassessment proceedings require disclosure of the computation, relevant allegations and supporting material before an order is made under Section 148A(3). Treating all bank credits as undisclosed turnover without furnishing the computation, and relying on allegations concerning fund parking, expenses and unsecured loans that were absent from the notice, converts the process into a roving inquiry rather than one based on definite aspects. The Section 148A(3) order, prior approval and Section 148 notice were quashed and remitted for fresh consideration after disclosure of the relied-upon material and a reasonable opportunity to respond.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4949






 Get Daily Updates