Centralised assessment transfers after searches coordinate connected investigations without finally determining the assessee's tax liability or assess...
Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
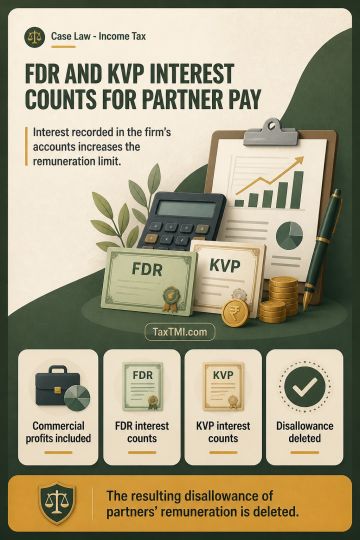
For computing the ceiling on partners' remuneration under section 40(b), book profit comprises the commercial profits shown in the partnership firm's profit and loss account, rather than only income assessed under the head of business or profession. Interest on FDRs and KVPs included in that account forms part of book profit even where treated as income from other sources. Excluding such interest from book profit is contrary to law, and the resulting disallowance of partners' remuneration is deleted.
For computing the ceiling on partners' remuneration under section 40(b), book profit comprises the commercial profits shown in the partnership firm's profit and loss account, rather than only income assessed under the head of business or profession. Interest on FDRs and KVPs included in that account forms part of book profit even where treated as income from other sources. Excluding such interest from book profit is contrary to law, and the resulting disallowance of partners' remuneration is deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4945






 Get Daily Updates