Centralised assessment transfers after searches coordinate connected investigations without finally determining the assessee's tax liability or assess...
Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
Page of 4929
Press 'Enter' after typing page number.
101 to 120 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
The first proviso to section 149(1)(b) preserves the...
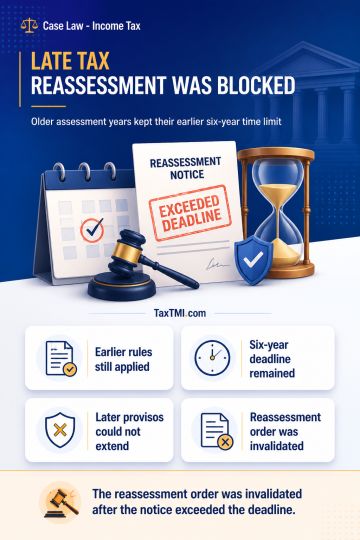
Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier assessment years.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
The first proviso to section 149(1)(b) preserves the reassessment limitation available under the pre-amendment regime for assessment years commencing on or before 1 April 2021. The fifth and sixth provisos regulate computation under the amended three-year or ten-year framework but cannot extend that preserved limitation. Consequently, a reassessment notice for assessment year 2015-16 issued after expiry of six years from the end of the relevant assessment year was time-barred, and the consequential reassessment order was invalidated.
The first proviso to section 149(1)(b) preserves the reassessment limitation available under the pre-amendment regime for assessment years commencing on or before 1 April 2021. The fifth and sixth provisos regulate computation under the amended three-year or ten-year framework but cannot extend that preserved limitation. Consequently, a reassessment notice for assessment year 2015-16 issued after expiry of six years from the end of the relevant assessment year was time-barred, and the consequential reassessment order was invalidated.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929