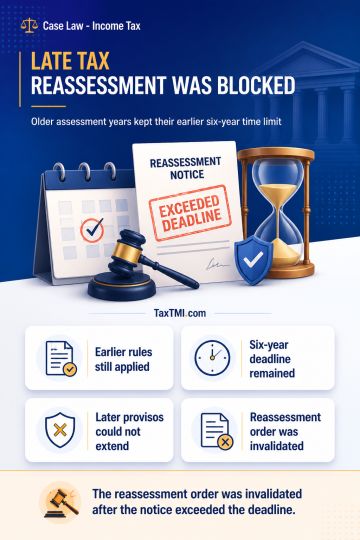
Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Page of 4925
Press 'Enter' after typing page number.
161 to 180 of 98494 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
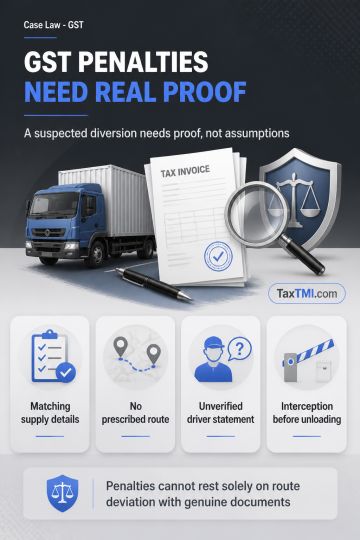
GST transit penalties require evidence of an existing statutory contravention rather than presumptions based on a vehicle's route or anticipated delivery. A place-of-supply entry consistent with the invoice and e-way bill undermines an allegation that goods were diverted to an undeclared local supply. The GST framework does not require a selling dealer to disclose or follow a particular transportation route; route deviation alone, where accompanying documents are genuine, does not establish contravention. An uncorroborated driver statement referring to an unverified third party, coupled with interception before unloading, is insufficient to prove unauthorised delivery or tax evasion.
GST transit penalties require evidence of an existing statutory contravention rather than presumptions based on a vehicle's route or anticipated delivery. A place-of-supply entry consistent with the invoice and e-way bill undermines an allegation that goods were diverted to an undeclared local supply. The GST framework does not require a selling dealer to disclose or follow a particular transportation route; route deviation alone, where accompanying documents are genuine, does not establish contravention. An uncorroborated driver statement referring to an unverified third party, coupled with interception before unloading, is insufficient to prove unauthorised delivery or tax evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925