Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
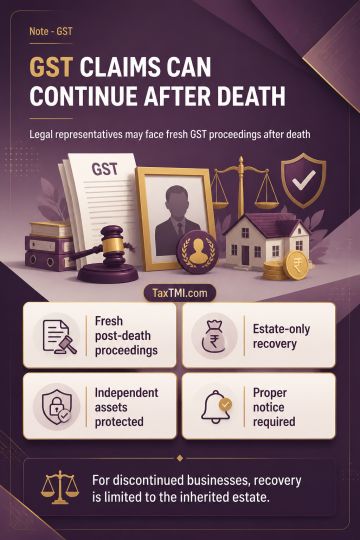
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Page of 4935
Press 'Enter' after typing page number.
381 to 400 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
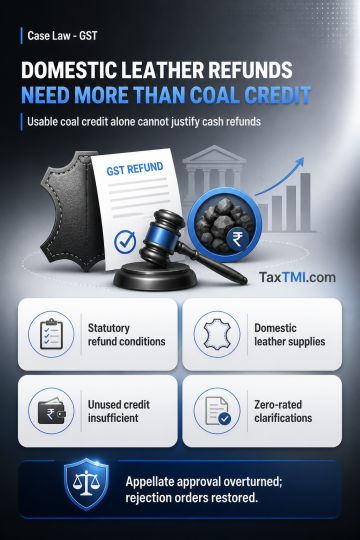
Refund of accumulated Compensation Cess input tax credit on coal used to manufacture leather products for domestic supplies requires independent satisfaction of statutory refund conditions for an inverted tax structure. Eligibility to avail such credit, and the absence of a blocked-credit restriction, do not by themselves establish entitlement to a cash refund. Inability to utilise the credit against other liabilities cannot independently create a refund right, and the refund formula or procedure cannot create substantive entitlement where statutory conditions are unmet. Clarifications concerning zero-rated supplies did not establish eligibility for the domestic supplies. The appellate order allowing the claims was set aside and the rejection orders were restored.
Refund of accumulated Compensation Cess input tax credit on coal used to manufacture leather products for domestic supplies requires independent satisfaction of statutory refund conditions for an inverted tax structure. Eligibility to avail such credit, and the absence of a blocked-credit restriction, do not by themselves establish entitlement to a cash refund. Inability to utilise the credit against other liabilities cannot independently create a refund right, and the refund formula or procedure cannot create substantive entitlement where statutory conditions are unmet. Clarifications concerning zero-rated supplies did not establish eligibility for the domestic supplies. The appellate order allowing the claims was set aside and the rejection orders were restored.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935