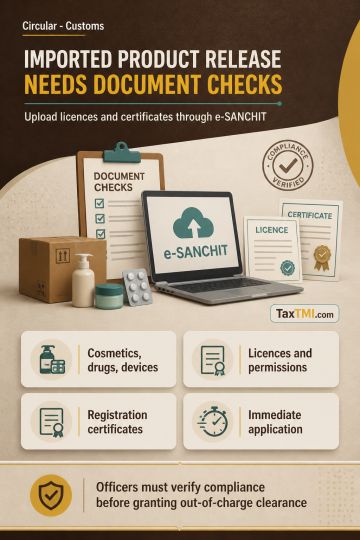
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
Refund of accumulated Compensation Cess input tax credit on coal used to manufacture leather products for domestic supplies requires independent satisfaction of statutory refund conditions for an inverted tax structure. Eligibility to avail such credit, and the absence of a blocked-credit restriction, do not by themselves establish entitlement to a cash refund. Inability to utilise the credit against other liabilities cannot independently create a refund right, and the refund formula or procedure cannot create substantive entitlement where statutory conditions are unmet. Clarifications concerning zero-rated supplies did not establish eligibility for the domestic supplies. The appellate order allowing the claims was set aside and the rejection orders were restored.
Refund of accumulated Compensation Cess input tax credit on coal used to manufacture leather products for domestic supplies requires independent satisfaction of statutory refund conditions for an inverted tax structure. Eligibility to avail such credit, and the absence of a blocked-credit restriction, do not by themselves establish entitlement to a cash refund. Inability to utilise the credit against other liabilities cannot independently create a refund right, and the refund formula or procedure cannot create substantive entitlement where statutory conditions are unmet. Clarifications concerning zero-rated supplies did not establish eligibility for the domestic supplies. The appellate order allowing the claims was set aside and the rejection orders were restored.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935