Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Page of 4934
Press 'Enter' after typing page number.
321 to 340 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
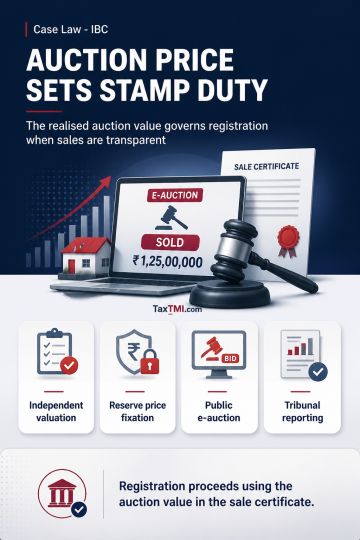
Stamp duty on a sale certificate issued following an insolvency liquidation e-auction is determined by the auction value where the process establishes the assets' true market value. The expression "Civil Court" in Article 16 extends to an auction conducted by a liquidator appointed under the insolvency framework, following independent valuation, reserve-price fixation, public e-auction and reporting to the Tribunal. An ASR-based valuation cannot displace the realised auction value without a valid basis to find intentional suppression or reduction of value to evade stamp duty. Registration is consequently to proceed on the auction value recorded in the liquidator's sale certificate.
Stamp duty on a sale certificate issued following an insolvency liquidation e-auction is determined by the auction value where the process establishes the assets' true market value. The expression "Civil Court" in Article 16 extends to an auction conducted by a liquidator appointed under the insolvency framework, following independent valuation, reserve-price fixation, public e-auction and reporting to the Tribunal. An ASR-based valuation cannot displace the realised auction value without a valid basis to find intentional suppression or reduction of value to evade stamp duty. Registration is consequently to proceed on the auction value recorded in the liquidator's sale certificate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934