Composite GST notices across tax periods breach separate limitation requirements, permitting fresh period-compliant proceedings where lawfully availab...
Bank-account freezing under anti-money-laundering law requires recorded reasons; writ review remains available despite an alternative statutory remedy...
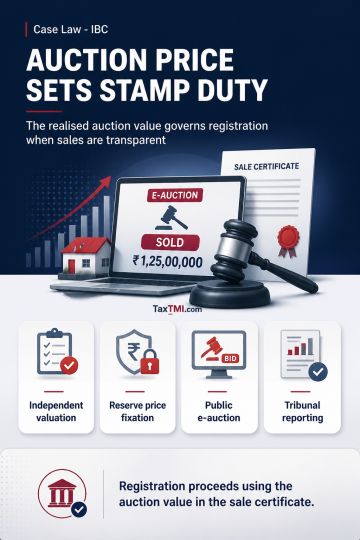
Stamp duty on a sale certificate issued following an insolvency liquidation e-auction is determined by the auction value where the process establishes the assets' true market value. The expression "Civil Court" in Article 16 extends to an auction conducted by a liquidator appointed under the insolvency framework, following independent valuation, reserve-price fixation, public e-auction and reporting to the Tribunal. An ASR-based valuation cannot displace the realised auction value without a valid basis to find intentional suppression or reduction of value to evade stamp duty. Registration is consequently to proceed on the auction value recorded in the liquidator's sale certificate.
Stamp duty on a sale certificate issued following an insolvency liquidation e-auction is determined by the auction value where the process establishes the assets' true market value. The expression "Civil Court" in Article 16 extends to an auction conducted by a liquidator appointed under the insolvency framework, following independent valuation, reserve-price fixation, public e-auction and reporting to the Tribunal. An ASR-based valuation cannot displace the realised auction value without a valid basis to find intentional suppression or reduction of value to evade stamp duty. Registration is consequently to proceed on the auction value recorded in the liquidator's sale certificate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935