Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
Page of 4934
Press 'Enter' after typing page number.
341 to 360 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
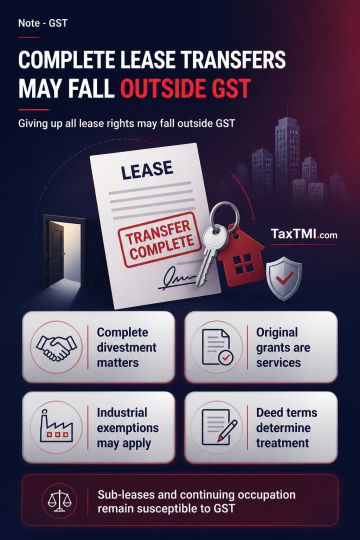
GST treatment of leasehold transfers depends on whether the transaction is an original grant, sub-lease, or complete assignment. An original grant of a lease, tenancy, easement or licence to occupy land is classified as a supply of services; qualifying long-term industrial leases may receive the stated exemption for upfront amounts. A complete assignment, where the outgoing lessee transfers the whole residual term, possession, building and associated benefits and retains no reversionary or possessory interest, may constitute transfer of an immovable-property interest rather than a taxable service. Consideration labels are not decisive; the deed, lessor consent, assignee substitution and future rent obligations determine characterisation. Sub-leases or continuing occupation arrangements remain susceptible to GST.
GST treatment of leasehold transfers depends on whether the transaction is an original grant, sub-lease, or complete assignment. An original grant of a lease, tenancy, easement or licence to occupy land is classified as a supply of services; qualifying long-term industrial leases may receive the stated exemption for upfront amounts. A complete assignment, where the outgoing lessee transfers the whole residual term, possession, building and associated benefits and retains no reversionary or possessory interest, may constitute transfer of an immovable-property interest rather than a taxable service. Consideration labels are not decisive; the deed, lessor consent, assignee substitution and future rent obligations determine characterisation. Sub-leases or continuing occupation arrangements remain susceptible to GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934