Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
Page of 4934
Press 'Enter' after typing page number.
341 to 360 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
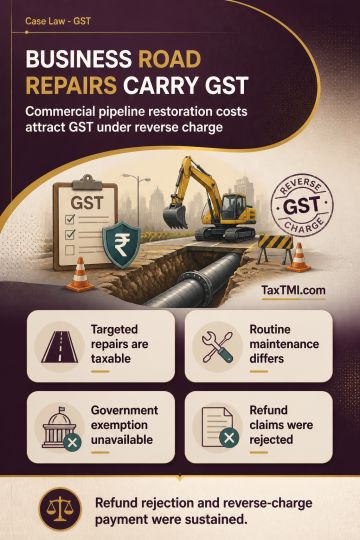
Road restoration charges paid for request-driven repair after excavation for commercial pipeline laying constitute consideration for a taxable service rather than compensatory damages. Routine public-road maintenance differs from targeted restoration supplied to a business entity; consequently, non-supply treatment and the governmental-services exemption do not apply, and tax under reverse charge remains payable. Prior refund sanctions in other jurisdictions and unsubstantiated double-taxation claims do not displace that mechanism. Electronic GST proceedings remain valid where portal records authenticate the application, notice, replies and orders, and the notice gave adequate factual and legal particulars without prejudice despite no physical DIN. The refund rejection and reverse-charge payment were sustained.
Road restoration charges paid for request-driven repair after excavation for commercial pipeline laying constitute consideration for a taxable service rather than compensatory damages. Routine public-road maintenance differs from targeted restoration supplied to a business entity; consequently, non-supply treatment and the governmental-services exemption do not apply, and tax under reverse charge remains payable. Prior refund sanctions in other jurisdictions and unsubstantiated double-taxation claims do not displace that mechanism. Electronic GST proceedings remain valid where portal records authenticate the application, notice, replies and orders, and the notice gave adequate factual and legal particulars without prejudice despite no physical DIN. The refund rejection and reverse-charge payment were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934