Approved gratuity fund provisions remain deductible despite general actual-payment requirements, preventing revision of the allowed gratuity deduction...
Verification of intangible software expenditure and duplicated disallowances requires record-based reassessment before depreciation and income computa...
Cash receipt aggregation requires a single transaction, event or occasion; separate partner capital contributions cannot attract cash-receipt penaltie...
Page of 4927
Press 'Enter' after typing page number.
81 to 100 of 98535 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
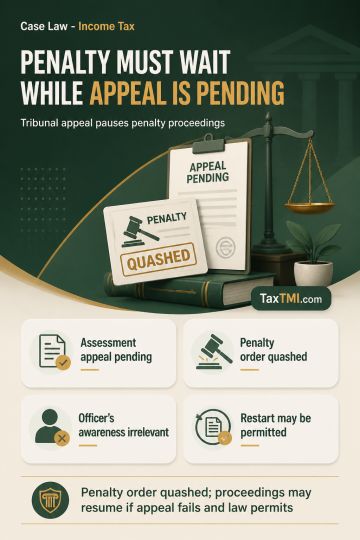
Section 275(1)(a) requires penalty proceedings to remain in abeyance while an appeal against the relevant assessment order is pending before the Appellate Tribunal. A penalty order for under-reporting of income passed during that pendency is contrary to the statutory bar, regardless of whether the Assessing Officer had been informed of the appeal. The penalty order was quashed, with liberty to recommence penalty proceedings if the assessment appeal is decided against the assessee and the law permits.
Section 275(1)(a) requires penalty proceedings to remain in abeyance while an appeal against the relevant assessment order is pending before the Appellate Tribunal. A penalty order for under-reporting of income passed during that pendency is contrary to the statutory bar, regardless of whether the Assessing Officer had been informed of the appeal. The penalty order was quashed, with liberty to recommence penalty proceedings if the assessment appeal is decided against the assessee and the law permits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927